



Quick Summary
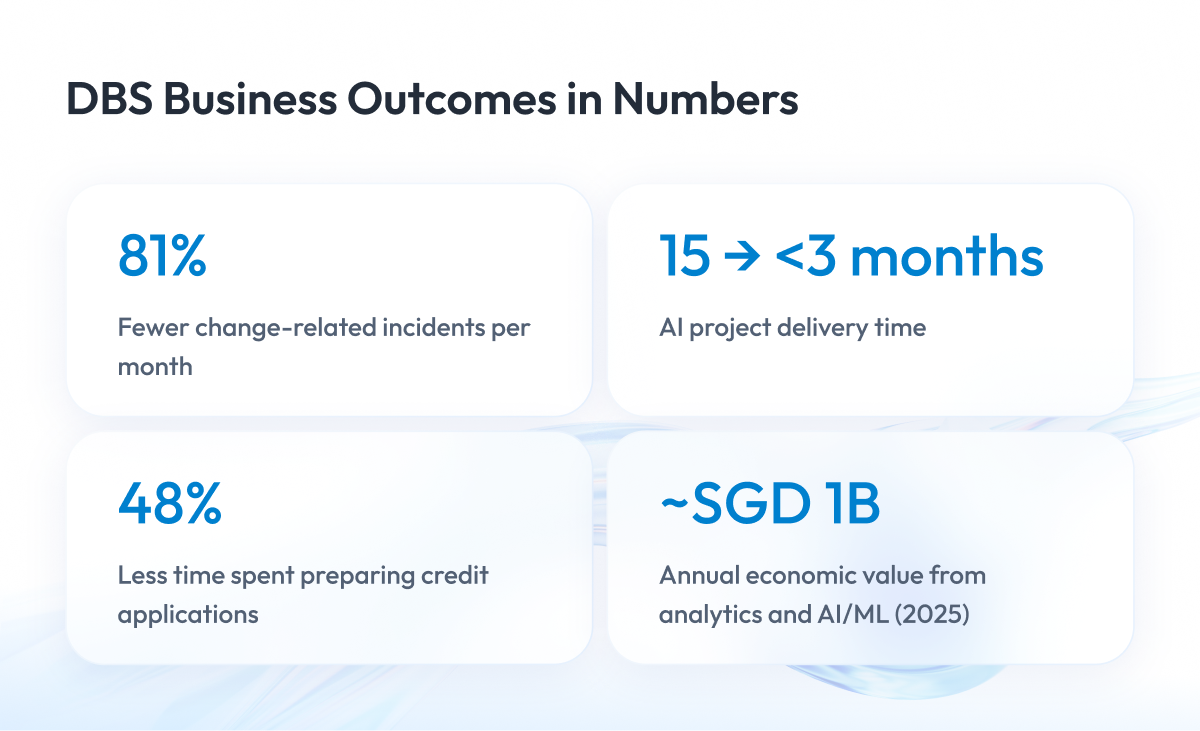
- DBS reported approximately SGD 1 billion in economic value from analytics and AI/ML in 2025, across 2,000+ models and 430+ use cases.
- Shared data and model platforms helped reduce AI project timelines from 15 months to under three months.
- AI risk scoring expanded change-request checks from 5% to 100%, alongside 81% fewer change-related incidents.
- Workflow improvements cut credit-application preparation time by 48%, trade-condition processing by 60%, and call handling by up to 20%.
- DBS’s approach connects AI to specific workflows, shared ownership, and measurable results, with testing and controls supporting delivery.
DBS once checked only 5% of technology change requests. In 2024, it reported that AI risk scoring had expanded those checks to 100%, alongside an 81% decrease in the monthly average of change-related incidents.
That result explains more about its AI programme than the number of models it deployed.
By 2025, DBS reported approximately SGD 1 billion in economic value from data analytics and AI/ML. More than 2,000 models supported over 430 use cases.
Behind that headline were specific changes to everyday work:
- Credit applications: 48% less preparation time.
- Trade conditions: 60% less processing time.
- Customer calls: up to 20% lower handling time.
These results came from different systems and reporting periods. Each becomes more useful when connected to the decision, workflow, and measurement behind it.
The Problem: Faster Delivery Needed Stronger Controls
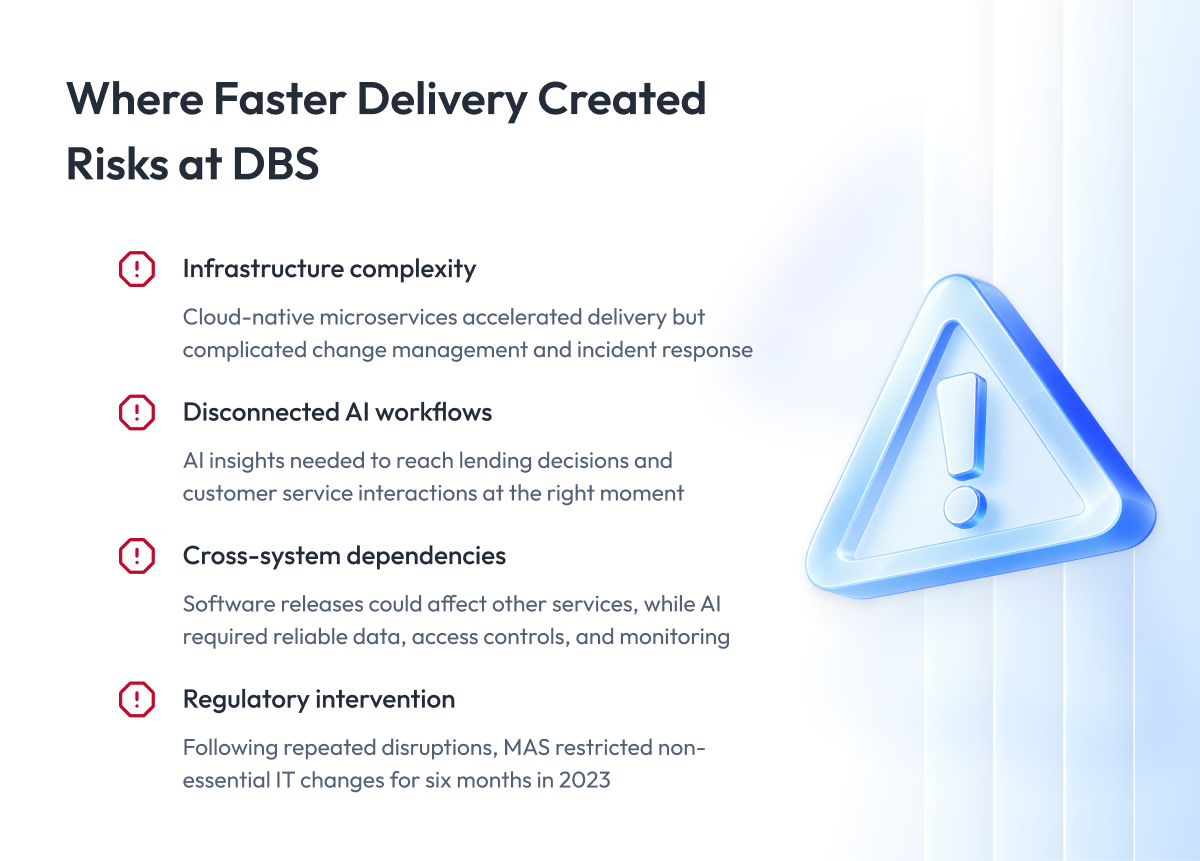
DBS had already moved toward cloud-native microservices. Its 2023 CIO statement acknowledged the tradeoff: faster execution brought greater infrastructure complexity.
The bank needed stronger oversight of how systems changed and how incidents were handled.
AI introduced another integration problem. A prediction could be accurate but still arrive outside the workflow where someone needed to act.
- Lending: application preparation, financial analysis, and approvals crossed multiple roles.
- Service: officers needed current policy answers during live customer calls.
- Software delivery: one team’s release could affect services elsewhere.
- Data: reusable models required dependable inputs, permissions, and monitoring.
In November 2023, repeated disruptions led the Monetary Authority of Singapore to impose a six-month pause on non-essential IT changes and new business acquisitions.
DBS had to improve reliability while continuing its broader AI transformation. Delivery speed and operational control had become inseparable.
What DBS Delivered
The public disclosures show shared platforms, lending tools, release controls, and service assistants developing over several years.
These are reported milestones, rather than a claim that every initiative followed one fixed sequence.
| Period | What DBS delivered | Operational significance |
| 2021 | Full deployment of ALAN, its shared AI/ML platform | Reusable models and data with governance requirements |
| 2023 | GLOW lending workbench and CRANE risk models documented at Investor Day | Less preparation work and earlier borrower-risk alerts |
| 2024 | AI change-risk scoring and CSO Assistant rollout plans | Wider change checks and assistance during customer calls |
| 2025 | More than 2,000 models across 430+ use cases | Approximately SGD 1 billion in reported analytics and AI/ML value |
| 2025–2026 | Reported results from GenAI service tools | Shorter handling time and improved customer satisfaction |
The capabilities addressed different parts of banking operations.
| Layer | Capability | What it does |
| Data and models | ADA and ALAN | Support governed data access and model reuse |
| Credit | GLOW and CRANE | Connect lending preparation with borrower-risk review |
| Technology operations | AI change-risk scoring | Assess software changes before release |
| Employee assistance | CSO Assistant | Transcribe calls, retrieve information, and prepare service records |
| Customer service | DBS Joy | Answer defined service queries with specialist escalation |
How DBS Built It
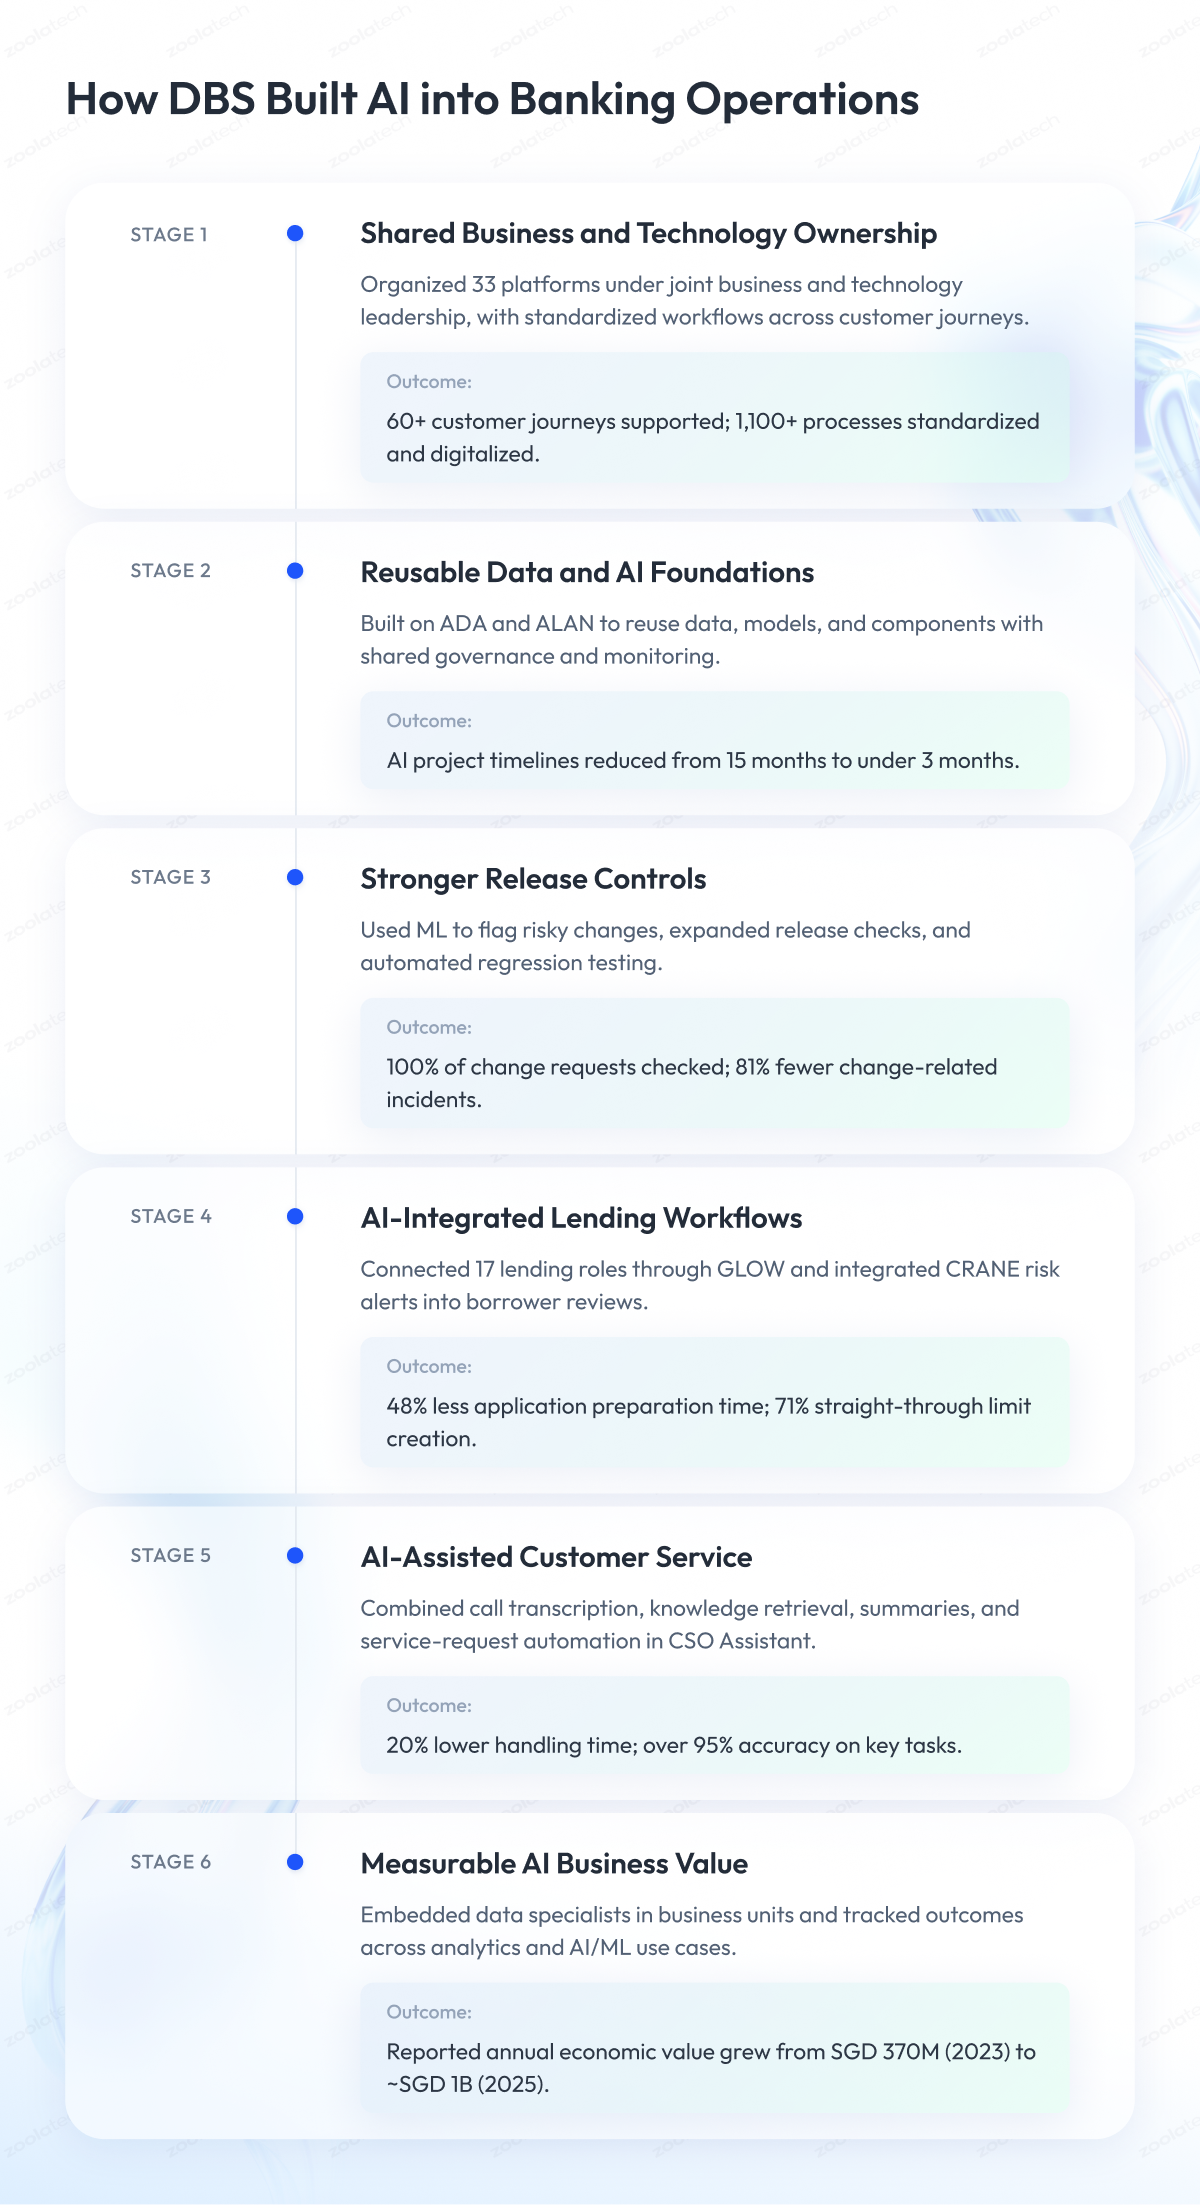
Six decisions show how the platform work connected to operational results.
Stage 1: Put business and technology under shared ownership
DBS organised around 33 platforms jointly led by business and technology leaders. Its transformation partner describes the arrangement as “2-in-a-box.”
The business leader brought the operational objective. The technology leader brought responsibility for the systems needed to achieve it.
Managing Through Journeys extended that approach across more than 60 customer journeys.
The supporting process work was substantial. By 2023, DBS had standardised and digitalised more than 1,100 processes through its Intelligent Business Process Management system.
This gave teams defined workflows to improve. It also gave them something concrete to measure: preparation time, manual handoffs, release risk, or service handling.
Stage 2: Reuse the data, models, and controls
DBS reported full deployment of ALAN in 2021. ADA provided the data foundation; ALAN supported model development and reuse.
The bank’s governance framework includes model registration, data classification, approvals, and monitoring after deployment.
Teams could reuse shared assets while retaining checks around each application.
In October 2025, DBS linked reusable components, templates, and automation to AI project timelines falling from 15 months to under three months.
Its 2025 CIO statement reported two additional delivery measures:
- Model deployment cycles: seven to ten weeks.
- Code deployment time: 25% lower.
These describe different parts of delivery. A shorter project timeline is not the same measurement as a faster model or code deployment.
Stage 3: Check the changes that could break service
After the regulatory pause, DBS strengthened its release controls. It trained an ML model on historical change requests to identify risk before changes reached production.
The bank later reported that the pause would end as scheduled, while acknowledging that further resilience work remained.
Its 2024 CIO statement reported change-request checks expanding from 5% to 100%. The monthly average of change-related incidents fell 81%.
Testing improved too. More than 100 applications underwent near-production testing. By 2025, over 85% of regression testing was automated.
These improvements happened together. DBS does not isolate AI as the sole cause of the incident reduction.
For a related resilience example, see Zoolatech’s multi-region payments platform case study.
Stage 4: Put credit predictions inside the lending workflow
DBS’s 2023 credit-risk presentation shows where lending work changed. GLOW, its Global Lending Online Workbench, connected 17 user roles in one workflow.
The workbench combined financial spreading and analysis with application preparation and processing.
| GLOW workflow | Reported result |
| Credit-application preparation | 48% less time |
| Financial-analysis preparation | 30% less time |
| Limit creation | 71% straight-through processing |
CRANE addressed borrower monitoring. Its risk signals reached GLOW for review, connecting predictions to the people responsible for investigating them.
The presentation reports timely alerts for more than 73,000 borrowers.
An extension combining CRANE with cash-flow modelling identified over SGD 80 million in at-risk exposures during the COVID-19 moratorium.
That figure measures exposure identified, not money saved. Likewise, straight-through limit creation does not mean automated approval of every lending decision.
For a related workflow example, read Zoolatech’s Credible loan-workflow automation case study.
Stage 5: Reduce the work around customer conversations
CSO Assistant targeted tasks service officers already performed. The July 2024 announcement describes an in-house system combining an LLM, telephony, and speech recognition.
The assistant handled four jobs:
- Transcribe calls.
- Retrieve answers from the bank’s knowledge base.
- Draft conversation summaries.
- Pre-fill service-request fields.
Pilots began in October 2023. The July 2024 rollout plan covered 500 Singapore service officers and forecast up to 20% lower handling time.
By March 2026, DBS’s chief data and transformation officer reported that reduction as achieved.
Accuracy exceeded 95% on key tasks such as transcription and recommendations. That is a task-level measure, rather than proof that every generated answer was correct.
DBS Joy brought a defined service scope directly to customers. Its enhanced GenAI version included response checks, specialist escalation, and conversation review.
The 2025 Institutional Banking report records:
- More than 20,000 unique Joy users.
- Roughly 15,000 monthly chat sessions.
- A 23% improvement in satisfaction scores over six months.
The same report gives a separate processing result: 60% less time for trade conditions.
That improvement applies to a specific task. It does not describe the entire trade-finance lifecycle.
For a related implementation, see Zoolatech’s AI multilingual chatbot for financial assistance case study.
Stage 6: Keep measurement close to the business
DBS’s data chapter includes 700 data professionals, including 250 data scientists, embedded in business units.
The arrangement combines shared technical capabilities with knowledge of the work being changed.
Its annual disclosures show the growth in reported value and adoption:
| Reporting year | Analytics and AI/ML economic value | Scale |
| 2023 | SGD 370 million | 800+ models; 350 use cases |
| 2024 | More than SGD 750 million | 1,500+ models; 370+ use cases |
| 2025 | Approximately SGD 1 billion | 2,000+ models; 430+ use cases |
The figures come from DBS’s annual reporting, including its 2024 customer-innovation review.
On the February 2026 analyst call, CEO Tan Su Shan explained the SGD 1 billion figure through A/B testing around traditional machine learning.
She also said generative and agentic AI were harder to measure.
The headline therefore cannot be presented as SGD 1 billion in GenAI savings or net profit. It is DBS’s reported economic-value measure for the broader analytics and AI/ML programme.
Business Outcomes in Numbers
Each result belongs to a particular system and reporting period. The tables preserve those boundaries.
Lending and customer operations
| Metric | Result | Scope |
| Credit-application preparation | 48% less time | GLOW; 2023 Investor Day |
| Financial-analysis preparation | 30% less time | GLOW; 2023 Investor Day |
| Limit creation | 71% straight-through processing | Workflow processing, not all lending decisions |
| Call handling | Up to 20% less time | CSO Assistant; achieved result reported March 2026 |
| Trade-condition processing | 60% less time | 2025 Institutional Banking report |
| Joy satisfaction scores | 23% improvement | Over six months; reported for 2025 |
Delivery and operational control
| Metric | Result | Scope |
| Change-request checks | 5% to 100% coverage | AI risk scoring; reported for 2024 |
| Change-related incidents | 81% lower monthly average | Alongside wider control improvements |
| AI project duration | 15 months to under three months | DBS October 2025 account |
| Model deployment cycles | Seven to ten weeks | 2025 CIO statement |
| Code deployment time | 25% lower | 2025 CIO statement |
| Regression testing | More than 85% automated | Coverage, not a defect-reduction percentage |
Figures that need a qualification
| Figure | What it means |
| Approximately SGD 1 billion | Reported analytics and AI/ML economic value in 2025; not GenAI savings |
| More than SGD 80 million | At-risk exposures identified; not realised savings |
| Over 95% accuracy | Selected service-assistant tasks; not every customer answer |
| Up to 20% lower call handling time | A forecast in July 2024, subsequently reported as achieved |
Conclusion
DBS’s strongest operational results follow specific decisions:
- Give business and technology joint responsibility for platforms.
- Reuse governed data and models across use cases.
- Expand change-risk checks as software delivery grows.
- Send borrower-risk signals into a review workflow.
- Put assistance inside calls and service documentation.
- Keep task results separate from enterprise value estimates.
The service disruptions belong in that story too. Extensive AI adoption did not remove the need for testing, recovery, and accountable operations.
For enterprises, the starting point is a workflow with a measurable problem. The platform, integration, and controls should serve that problem.
That connects legacy modernization with data analytics and AI and machine learning services.
Quality assurance supports the testing and release controls around those systems. Our guide to building scalable web applications covers the architecture underneath.
The next investment needs a clear answer to three questions: which task changes, who owns the result, and how will the improvement be measured?
Disclaimer: This is an independent look at DBS’s AI journey, based on public reports and other published sources. Zoolatech was not involved in the projects described.